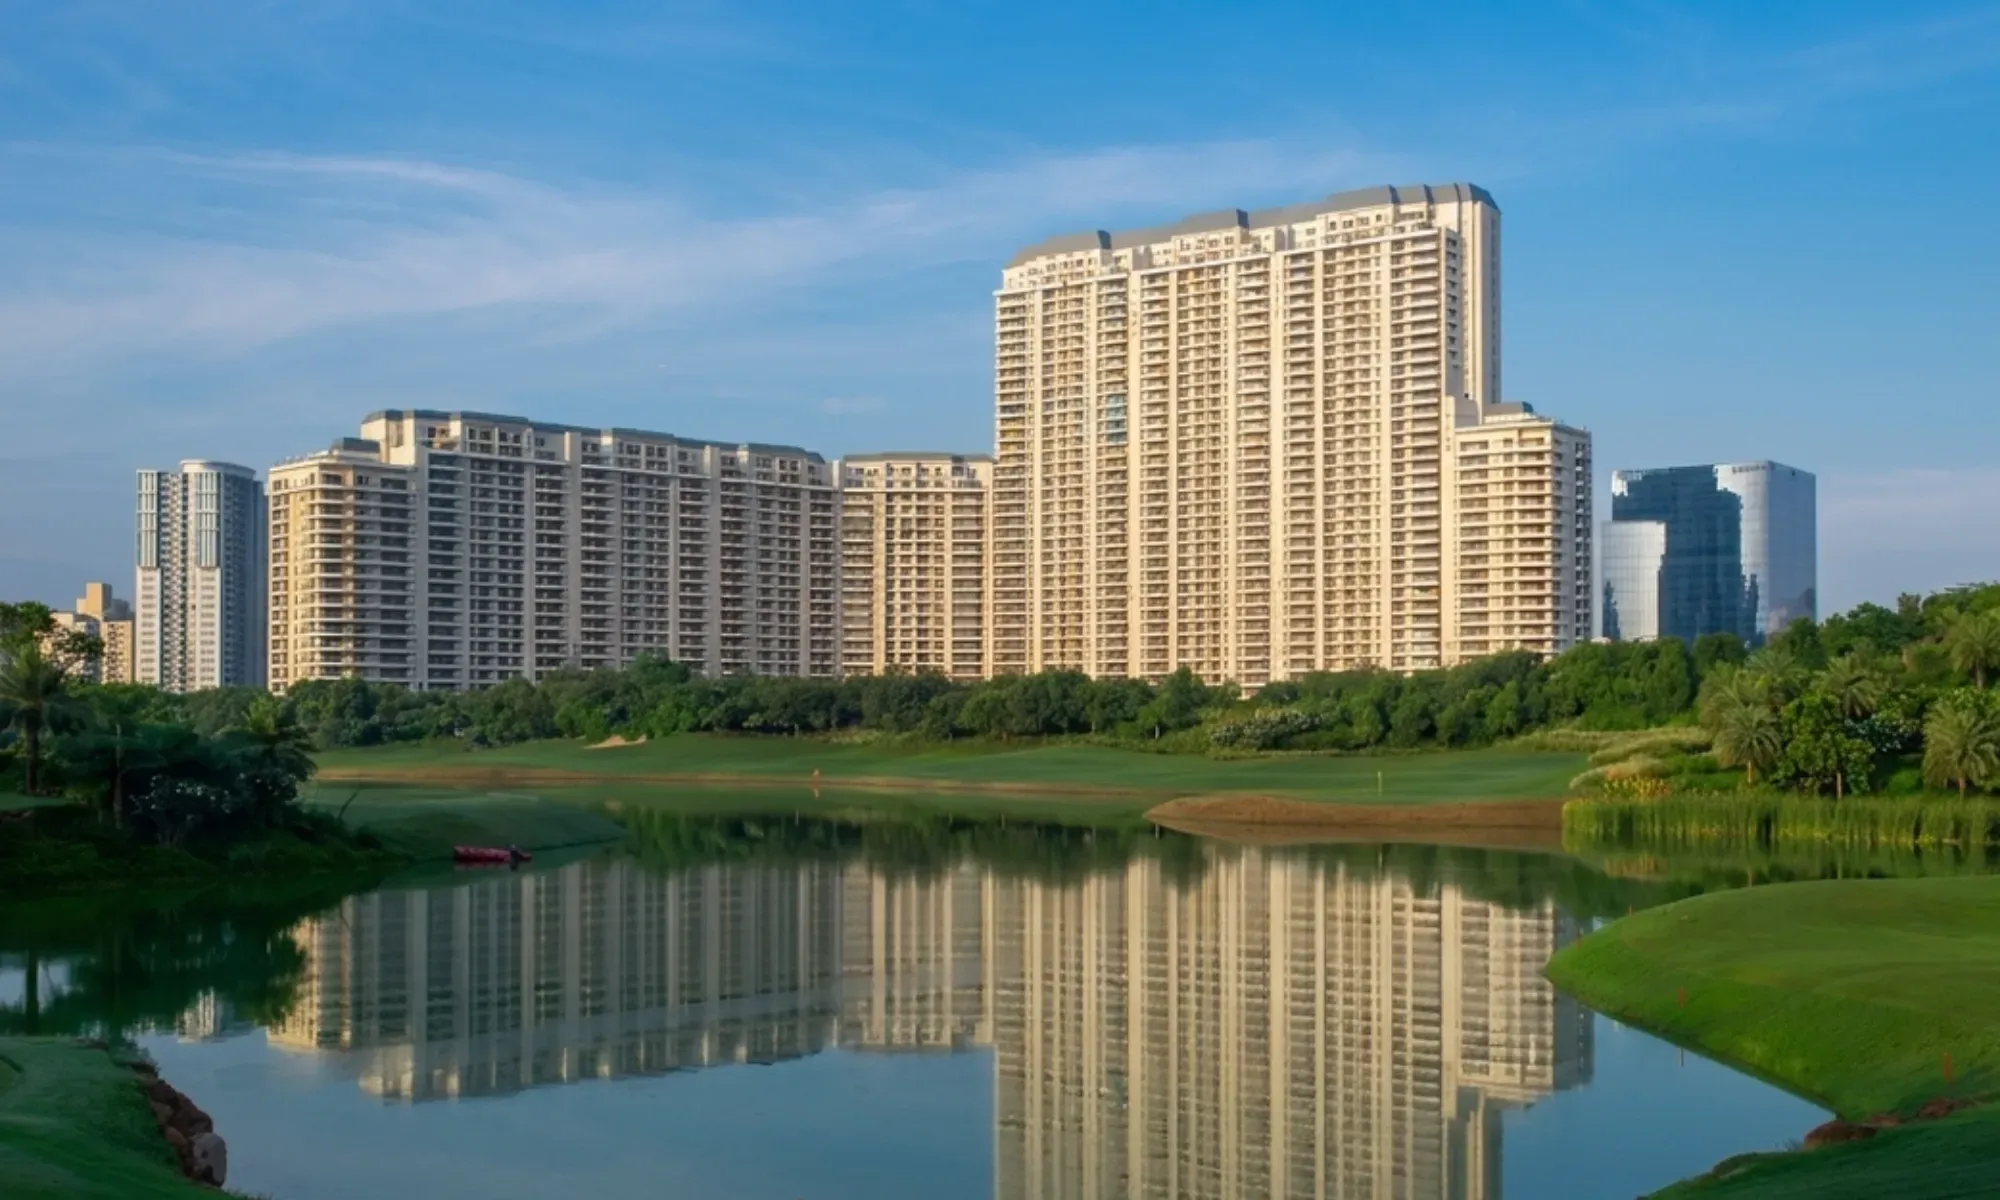
Investing in an ultra-luxury 3 BHK or 4 BHK apartment at the upcoming L&T Realty project in Sector 86, Gurugram is a massive milestone. Spanning a sprawling 20 acres and encompassing 3.6 million sq. ft. of high-rise development, this project is set to redefine luxury living in New Gurgaon.
However, buying a premium home valued upwards of ₹4.75 Crore requires a sharp financial strategy. Because this project is currently in its highly anticipated pre-launch phase, securing a home loan involves unique steps compared to buying a ready-to-move property.
This comprehensive guide breaks down everything you need to know about the current project status, home loan eligibility, out-of-pocket costs, and how to structure your financing.
Project Financial Status & RERA Compliance
Before approaching a bank, it is crucial to understand where the project stands in its lifecycle:
- Pre-Launch Status: L&T Realty secured this prime land parcel for approximately ₹1,123 Crore. However, official inventory sales and structural designs are still being finalized.
- HRERA Registration: The project currently does not have an active Haryana RERA (HRERA) registration number. Major commercial lenders like SBI, HDFC, and ICICI will only officially approve the project for retail home loans after the HRERA number is issued. You can read more about this on the legal due diligence page.
- Estimated Pricing: Market experts estimate the launch price will range between ₹18,000 and ₹22,000 per sq. ft., putting the starting ticket size for a 3 BHK at roughly ₹4.75 Crore. The price vs market rate analysis covers this in more detail.
- Prevailing Interest Rates: With the Reserve Bank of India's (RBI) current repo rate at 5.50%, buyers can expect floating luxury home loan interest rates to average between 8.55% and 9.25%, heavily depending on individual credit profiles.
Funding Limits: How Much Will the Bank Finance?
According to standard RBI home loan guidelines, properties valued above ₹75 Lakhs are subject to a maximum Loan-to-Value (LTV) ratio of 75%. This means the bank can cover up to 75% of the property's agreement value, leaving the remaining 25% to be funded by the buyer.
When preparing your budget, keep in mind that banks do not fund registration fees, stamp duty, or initial pre-launch booking tokens (Expression of Interest/EOI).
Estimated Cost Breakdown Example
| Expense Component | Who Pays? | Percentage of Cost | Estimated Amount (On a ₹4.75 Cr Base Price) |
|---|---|---|---|
| Property Agreement Value | Bank Loan | Up to 75% | ₹3.56 Crore |
| Down Payment | Buyer (Own Funds) | Minimum 25% | ₹1.19 Crore |
| Stamp Duty & Registration | Buyer (Own Funds) | ~5% to 7% in Haryana | ₹23.7 Lakh to ₹33.2 Lakh |
| Total Liquid Cash Required | Buyer | ~32% of total cost | ₹1.42 Crore to ₹1.52 Crore |
Understanding the Construction-Linked Payment Plan (CLP)
Because this is a brand-new high-rise development, L&T Realty will primarily offer a Construction-Linked Payment Plan (CLP). Financing a CLP property works differently than buying a finished home:
- Tranche-Based Disbursements: The bank will not release the ₹3.56 Crore loan in one lump sum. Instead, funds are released in percentages directly to L&T Realty as specific construction milestones are achieved (e.g., completion of excavation, plinth level, or specific floor slabs).
- Pre-EMI Interest: During the 3-to-5-year construction window, you generally only pay Pre-EMI. This is the interest calculated only on the amount the bank has disbursed so far, not the full sanctioned loan amount.
- Full EMIs: Your full EMI payments, covering both the principal amount and the interest, will only begin after the developer hands over the physical possession of your apartment. The possession date and timeline page tracks these updates.
Your 4-Step Home Loan Roadmap
To ensure a smooth financing experience, follow this strategic timeline:
Step 1: Secure a Personal Pre-Approval (Right Now)
Do not wait for the project launch to talk to lenders. Approach premium banking institutions for an income-based pre-approved loan. This determines your exact borrowing capacity based on your salary or business cash flows, giving you the clarity needed to choose between a 3 BHK or a larger 4 BHK layout.
Step 2: Optimize Your Credit Score
To qualify for the lowest possible interest rate margins, aim for a CIBIL score of 750 or above. Avoid opening new lines of credit or making heavy credit card purchases in the months leading up to your loan application.
Step 3: Verify the APF Number (At Project Launch)
Once L&T Realty receives its HRERA number and officially launches the project, major banks will audit the land titles and assign an Approved Project Financial (APF) number to the development. Choosing a bank that has already issued an APF number for L&T Sector 86 will reduce your individual loan processing time to just a few business days.
Step 4: Execute the Tripartite Agreement
Before the first loan disbursement is made, you, L&T Realty, and your chosen bank will sign a Tripartite Agreement. This document outlines the bank's responsibility to pay the developer on time, and the developer's commitment to transfer the property title to the bank as security until your loan is fully repaid.
Final Verdict: Is It Right For You?
Financing an ultra-luxury home in New Gurgaon requires significant liquid capital upfront, but leveraging a Construction-Linked Plan allows you to manage your cash flows effectively during the building phase. By securing an income-based pre-approval today, you place yourself at the front of the line when L&T Realty officially opens its doors in Sector 86. For the booking process, see the how to book apartment guide.
Frequently Asked Questions
1. Can I get a home loan for L&T Sector 86 Gurgaon before RERA registration?
No. Major lenders like SBI, HDFC, and ICICI will only officially approve the project for retail home loans after the HRERA number is issued. You can secure an income-based pre-approval in the meantime.
2. What is the maximum home loan I can get on a ₹4.75 Crore property?
According to RBI guidelines, properties valued above ₹75 Lakhs are subject to a maximum Loan-to-Value (LTV) ratio of 75%. On a ₹4.75 Crore property, the bank can finance up to approximately ₹3.56 Crore.
3. How much liquid cash do I need to buy a 3 BHK at L&T Sector 86?
You should comfortably arrange at least ₹1.5 Crore in liquid capital to cover your down payment (minimum 25%) and statutory government dues like stamp duty and registration.
4. What is a Construction-Linked Payment Plan (CLP)?
In a CLP, the bank releases loan funds in percentages directly to the developer as specific construction milestones are achieved. You pay only Pre-EMI interest during construction, and full EMIs begin after possession.
5. What CIBIL score do I need for a luxury home loan?
Aim for a CIBIL score of 750 or above to qualify for the lowest possible interest rate margins on luxury home loans.